They can build a reliable financial routine even when paychecks arrive unpredictably. Create a baseline budget using the lowest monthly income you expect, keep a buffer equal to several months of expenses, and automate savings when any payment lands.
This piece lays out practical steps that work for contractors, freelancers, commission earners, and seasonal workers. Expect clear tactics on tracking cash flow, smoothing income, and aligning spending with irregular receipts to reduce stress and gain control.
Mastering Financial Stability with Irregular Income
This section breaks down practical steps to stabilize cash flow, allocate money to priorities, and build savings that absorb unpredictable pay. Each part centers on concrete actions: identifying income patterns, listing essential costs, creating baseline and zero-based budgets, and separating savings for specific uses.
Understanding Irregular and Variable Income Streams
Irregular income includes freelance pay, gig work, commissions, royalties, tips, and fluctuating business revenue. They should be tracked by date and amount for at least six to twelve months to calculate realistic averages and seasonal swings.
Create a simple spreadsheet or use budgeting software to log each deposit and its source. Record gross and net amounts, frequency (daily, weekly, monthly), and one-off windfalls. Calculate three figures: lowest monthly total, median monthly total, and 6–12 month average. Use the lowest-month figure for conservative planning and the average for growth goals.
Distinguish guaranteed variable income (e.g., recurring contract work) from truly unpredictable income (one-off gigs). Label irregular income sources by reliability, so he or she can weight them differently in budgets and decide which to treat as savings versus spending.
Establishing Essential and Fixed Expenses
Essential expenses are non-negotiable costs required for daily living and work: rent/mortgage, utilities, insurance, minimum debt payments, groceries, transportation, and business expenses tied to earning income. Fixed expenses recur with predictable amounts; variable expenses fluctuate but remain necessary.
Compile a list and prioritize by due date and legal consequence of nonpayment. Use direct debits or scheduled transfers to ensure bills are paid on time. If bills vary (electricity, fuel), calculate a 12-month average to include in the monthly baseline.
Tag each expense as essential/fixed, essential/variable, or nonessential. That labeling helps when income drops; he or she can trim nonessentials first and negotiate or defer variable essentials second (e.g., ask for a payment plan on medical bills).
Building a Baseline and Zero-Based Budget
A baseline budget covers essential expenses using a conservative income estimate, typically the lowest monthly total from historical data. This baseline becomes the minimum threshold that must be funded before discretionary spending.
A zero-based budget assigns every dollar an explicit job: bills, savings, taxes, and spending. Start with baseline essentials, then allocate to savings buckets (emergency, tax reserve, sinking funds), and finally to flexible spending. Each month, adjust allocations to reflect actual receipts.
Use a simple worksheet: row for each category, column for baseline amount, projected allocation, and actual. Reconcile at month-end. When income exceeds baseline, prioritize tax withholding and savings increases rather than immediately expanding lifestyle.
Creating and Maintaining an Emergency Fund
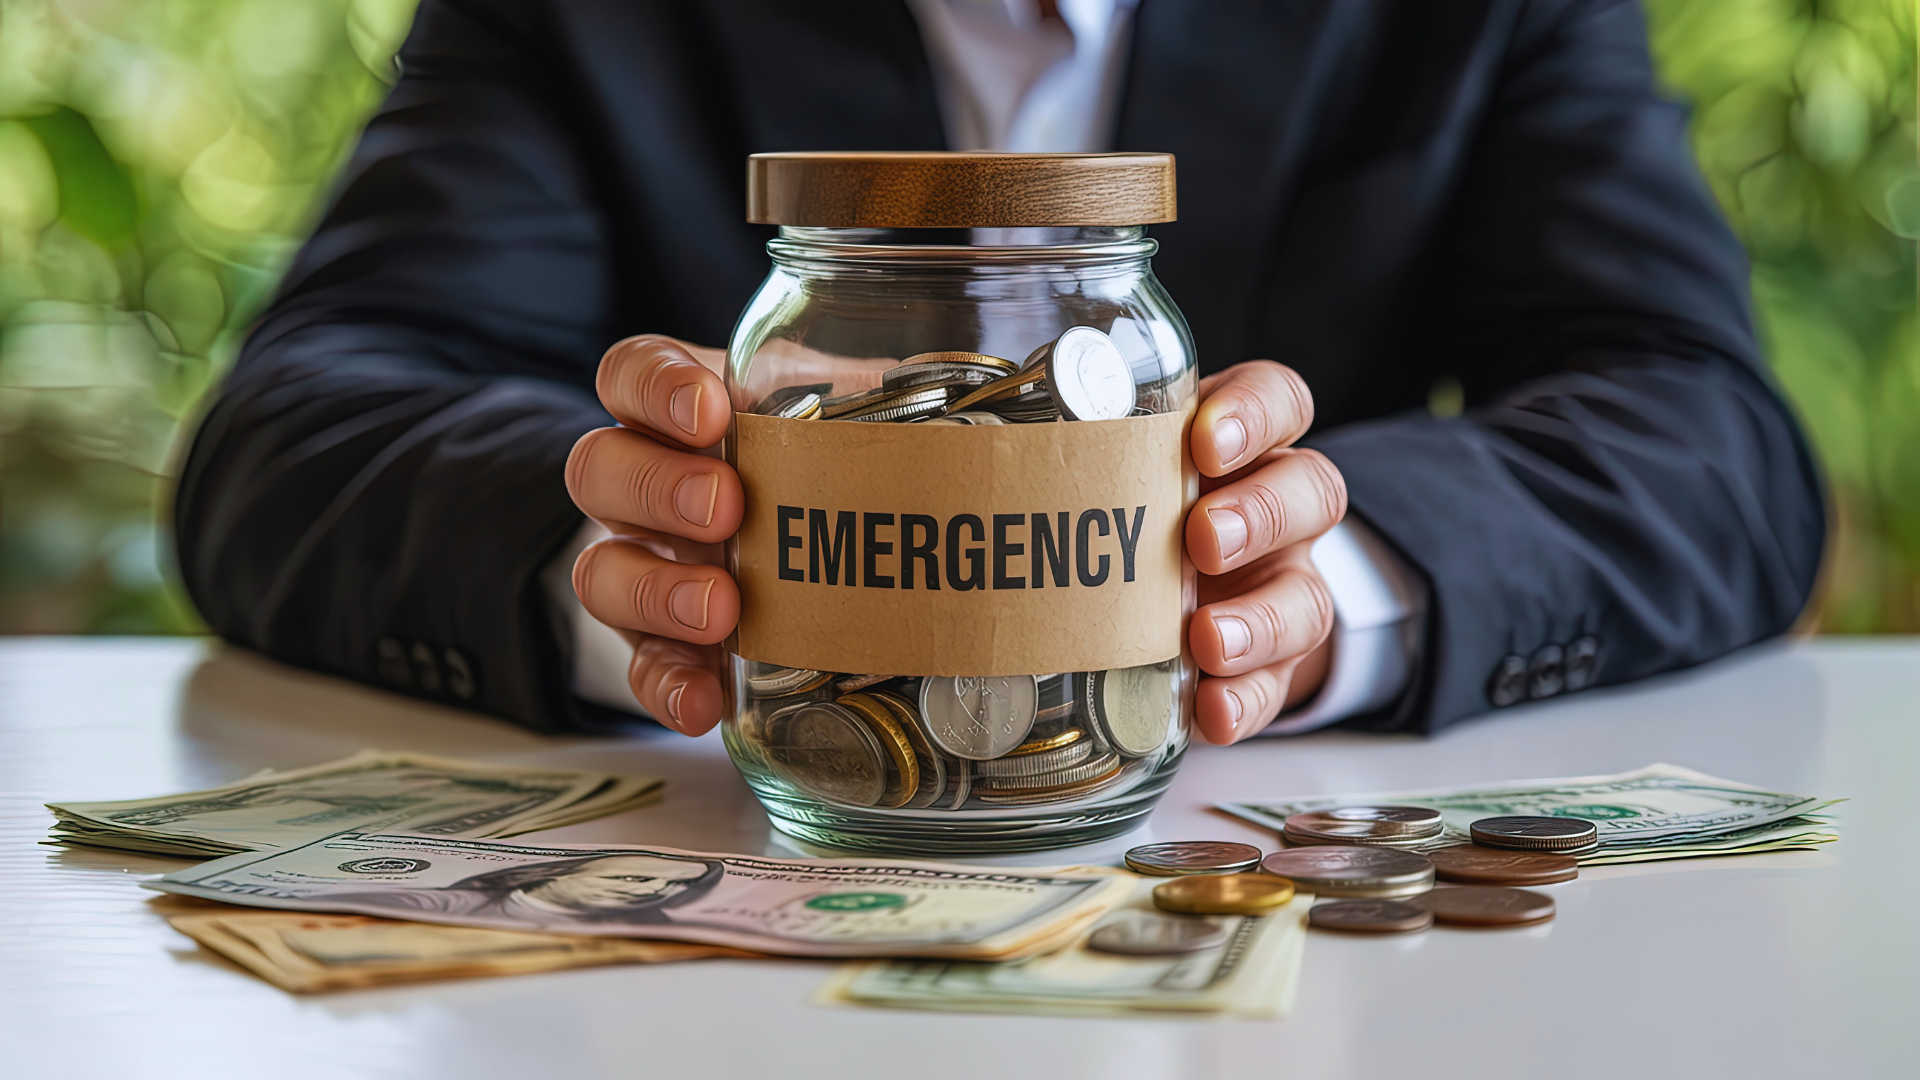
Target an emergency fund sized to income variability and job risk—commonly 3–12 months of essential expenses. For highly irregular earners, err toward 6–12 months to cover income gaps and unexpected costs.
Fund it consistently by automating transfers into a separate high-yield savings account on payday or weekly. If pay varies, set a percentage rule (e.g., 10–25% of each payment) to deposit when money arrives. Treat the fund as untouchable except for true emergencies.
Label the account clearly and avoid linking it to daily spending. Periodically reassess the target after major life changes (new client base, industry downturns) and increase contributions when monthly income exceeds the long-term average.
Separating Savings: Buffers, Emergency, and Sinking Funds
Use multiple accounts to prevent mixing goals. A buffer covers short-term timing gaps (2–4 weeks of variable expenses), the emergency fund covers major shocks (months of essentials), and sinking funds target planned but irregular costs (taxes, repairs, annual insurance).
Open at least three dedicated accounts or sub-accounts: Buffer, Emergency, and Sinking Funds. Automate or manually split each paycheck using set percentages tied to income patterns—e.g., 10% buffer, 15% emergency, 5% sinking—adjustable as cash flow stabilizes.
Designate sinking funds for specific items with target amounts and deadlines. Track progress visually (simple progress bars or spreadsheet formulas), so he or she can see when a fund is fully funded and pause contributions to redirect money elsewhere.
Tracking Cash Flow, Reviewing Income Patterns, and Adjusting Regularly
Track inflows and outflows daily or weekly to notice trends quickly. Use bank feeds or budgeting apps to categorize transactions automatically and reconcile them against income logs.
Review income patterns monthly and perform a deeper analysis every quarter. Compare actuals to the baseline and average figures; calculate variance percentages and identify seasonal peaks or troughs. When patterns shift permanently, reset the baseline and reallocate savings.
Establish simple rules for windfalls: allocate fixed percentages to taxes, emergency fund, retirement, and lifestyle. Reforecast cash flow when a major client is gained or lost, and adjust automatic transfers immediately to maintain coverage of essentials.
Prioritizing and Automating Savings and Expenses
Automation reduces decision fatigue and ensures priorities get funded first. Set up scheduled transfers: bill payments for fixed costs, percentage-based transfers to emergency and sinking funds, and a tax reserve account timed with typical tax deadlines.
Prioritize mandatory obligations and tax reserves before discretionary spending. When income proves higher than baseline, route the extra first to tax obligations and emergency savings, then to retirement and planned investments. If income is lower, pause discretionary and some sinking fund contributions temporarily.
Keep a “priority ladder” list that ranks transfers by importance and payment order. If an unexpected shortfall appears, follow the ladder to pause lower-priority moves without missing critical payments.
Leveraging Realistic Budgeting Strategies for Financial Confidence
Adopt conservative assumptions: budget to the lowest reliable monthly income and treat extra receipts as upside. Use a rolling three- to six-month average to smooth spikes and avoid overcommitting.
Combine zero-based budgeting for monthly accountability with percentage rules for savings and taxes. Use scenario planning: build a worst-case month, a typical month, and a best-case month, and create action plans for each (e.g., reduce subscriptions, delay nonessential purchases).
Regularly update goals and metrics: emergency fund target, buffer size, and sinking fund timelines. Measure financial confidence by tracking months of covered essential expenses and the trend in emergency savings; adjust contributions until coverage meets the chosen safety margin.